

Checkbook - Account Tracker analysis by Appwee
I like finance apps that stay out of the way, and Checkbook - Account Tracker is built around that idea. Instead of trying to become a complete banking hub, it gives me a digital place to record money coming in and going out, much like a traditional checkbook register. That narrow focus is its main appeal: I can see what I have committed to spend without handing the app a complicated job.
After using it as a simple account ledger, I found it most useful for people who still think in terms of a running balance. It suits someone tracking a checking account, monitoring household spending manually, or keeping an offline-style record alongside a bank app. It is less convincing for anyone expecting automatic bank synchronization, investment tools, bill negotiation, or a polished budgeting suite. This is a manual account tracker, not a replacement for online banking.
The app is free to install, carries an Everyone age rating, and comes from TinyWork Apps. Its average rating is 3.6 from around 9,300 ratings, with roughly 4,300 written reviews, while downloads have passed 100,000. Those figures suggest a useful but fairly specialized tool: people who want a straightforward register can find value here, although it clearly has limitations that keep it from satisfying every finance-app user.
How the current version feels in everyday use
A focused replacement for a paper register
The central workflow is easy to understand. I enter a transaction, record whether money was added or spent, and use the resulting balance as a quick reference. That approach feels familiar if I have ever maintained a paper checkbook, but it is more convenient than carrying a small notebook and doing every calculation by hand.
The strongest use case is daily balance awareness. Suppose I buy groceries, pay for parking, and make a small subscription payment before those transactions have fully settled at the bank. I can enter each item immediately and keep a more realistic view of what remains available. The value is not that the app knows what my bank knows; the value is that I can account for commitments before I forget them.
That distinction matters. A banking application normally shows posted transactions and may provide pending activity, but it can still be easy to overlook a payment made elsewhere or a check that has not cleared. A manually maintained register lets me record those items at the moment they happen. The trade-off is that the accuracy depends on my discipline. If I skip several purchases, the balance becomes misleading no matter how simple the interface is.
Where manual tracking works better than a full budget app
Many budgeting applications ask me to categorize purchases, set targets, connect accounts, and review charts. Those tools can be excellent for long-term planning, but they also create setup work. This app is better when my immediate question is simply, “What should my balance be after the payments I have made?”
For example, I could use it for a separate spending account rather than my entire financial life. I might record transfers into that account, log everyday purchases, and check the running figure before making a larger payment. This keeps the register meaningful without forcing me to classify every coffee or household item into a detailed budget structure.
It can also work for someone who wants a private manual record instead of linking financial accounts to a third-party service. That does not make the app automatically safer for every situation, and I would still treat a finance app carefully, but avoiding account connections can reduce the amount of setup and dependency involved. Users who prefer direct control over every entry may appreciate that simplicity.
The practical routine I recommend
I would not wait until the end of the week to enter transactions. The best routine is to add an item immediately after a purchase, then check the running balance before a large payment. A short daily review is more reliable than a long monthly cleanup, especially when several small card purchases are involved.
One useful habit is to record future commitments as soon as I know about them. A scheduled rent payment, a check written to someone, or an upcoming transfer can be included in the register so the displayed balance reflects money that is already spoken for. I would then compare the register with the bank account regularly, correcting mistakes before they accumulate.
Another practical tip is to use consistent descriptions. “Store” may be enough for a quick entry, but “weekly groceries” or “car repair deposit” makes an old transaction much easier to recognize. Since the app’s strength is the clarity of a personal record, vague notes weaken one of its main benefits.
What the app does not replace
I would keep the bank’s official app installed. The bank remains the place to confirm cleared transactions, available funds, fraud alerts, transfers, and account notices. This tracker is more like my personal accounting layer: it helps me anticipate the balance, while the bank remains the authoritative source for what actually happened.
I also would not choose it as my only tool for household budgeting if I need category reports or a shared financial plan. A spreadsheet or a more advanced budgeting service may be better when two people need to coordinate expenses, compare monthly categories, or plan savings goals. The advantage of this app is speed and focus, not breadth.
Evolution, limitations, and who should choose it
What the current release tells me
The current version is 2.1.2, and the app was released on July 24, 2015. That history gives the product a mature, established feel rather than the impression of a brand-new finance experiment. At the same time, I would not read an older release history as proof that the app has every modern convenience. The experience is best judged as a focused register, not against the feature list of newer financial platforms.
For existing users, a version such as 2.1.2 is important because it defines the experience they will actually use today. I would update when an update is available through the normal app store process, but I would also keep my expectations realistic: a version number alone does not turn a manual ledger into an automatically connected banking service.
The minimum operating-system requirement is Android 7.0, which makes the app accessible to many older Android devices. That can be useful for someone who wants to keep using an older phone as a dedicated household finance device. It also means the app may appeal to people who do not want to replace a functioning phone merely to run a basic account register.
The biggest remaining gaps
Manual entry is both the product’s defining strength and its main weakness. It gives me control, but it also creates opportunities for missed purchases, duplicate entries, and incorrect balances. A person who uses several cards or accounts may find the routine too demanding unless they are willing to maintain each register carefully.
The app is also not the right fit if I want automatic categorization or a broad financial dashboard. There is a meaningful difference between tracking a balance and understanding spending patterns. A register can tell me that money left an account, but it does not automatically turn that information into a complete monthly spending analysis.
Another limitation is that a simple ledger requires clear personal rules. I need to decide whether to record a card purchase when I make it or when the payment clears, and then use that choice consistently. For a checking account, immediate entry may help me avoid overspending. For a credit card, I might prefer a separate method because the purchase and the eventual account payment are different events. The app can support my record-keeping approach, but it cannot make that accounting decision for me.
People who need shared access should think carefully before choosing it. A household register is only useful when everyone records transactions in the same place and follows the same process. If one partner enters purchases while the other relies on a bank feed, the displayed balance may stop reflecting reality. A shared spreadsheet or collaborative budgeting product could be a better fit for that situation.
Cost and upgrade expectations
The app is free, with in-app purchases ranging from $0.99 to $19.99 per item. I would start with the free experience and decide whether it covers my routine before paying for anything. For a basic ledger, the important question is not whether the app has a long feature list; it is whether entering and reviewing transactions feels dependable enough to become a habit.
That pricing structure also means I would check the purchase details before confirming an upgrade. Someone who only needs a single running balance may have no reason to spend more, while a regular user may consider an optional purchase worthwhile if it removes a limitation that affects daily use. I would avoid paying simply because the app is inexpensive; the right test is whether it improves the specific workflow I actually use.
Who I would recommend it to
I would recommend it to a person who wants a digital checkbook register, prefers manual control, and is comfortable entering transactions. It is especially suitable for someone who wants to track one primary account, anticipate upcoming payments, or maintain a simple record without connecting bank credentials.
It may also help someone learning basic money management. Recording each purchase and watching the balance change can make spending feel more concrete than checking a bank total occasionally. Parents could use the same principle when teaching a teenager how deposits, withdrawals, and available balances relate to one another, provided they also explain that the app is a personal record rather than an official bank statement.
I would skip it if I want automatic synchronization, sophisticated reports, investment tracking, credit monitoring, or a complete household budgeting system. I would also hesitate if I know I will not enter transactions consistently. In that case, a bank app with automatic activity or a budgeting service that imports accounts would probably be more useful, even if it offers more complexity.
What I would watch before committing to it
My first test would be whether the entry routine remains comfortable after several days, not whether the initial setup feels simple. Finance tools succeed through repetition. If recording a payment takes too much attention, I will eventually postpone entries and lose confidence in the balance.
I would also watch how well the app fits my account structure. One account with regular transactions is a natural match. Several accounts, credit cards, cash spending, and shared household activity require more careful organization. Before moving completely away from paper or a spreadsheet, I would run the app alongside my existing method for a short period and compare balances.
Finally, I would decide what information belongs in the register. I would avoid storing unnecessary sensitive notes and would keep the bank’s official records available for verification. The app works best when it stays focused: record the transaction, understand the running balance, and use that information to make the next spending decision.
My overall view is positive but deliberately narrow. Checkbook - Account Tracker is a practical free finance app for people who want a straightforward digital register and are willing to maintain it themselves. Its age, focused design, and manual workflow are not automatically disadvantages; for the right user, they are exactly what keeps the tool manageable. But anyone seeking automation or full financial planning should choose a broader alternative.
I would install it when my goal is simple: keep a clear personal running balance and avoid forgetting payments. I would not treat it as a bank replacement, and I would not expect it to solve budgeting without my involvement. Used with that understanding, it can turn the old paper-checkbook habit into a convenient everyday routine without adding the weight of a full financial management system.
Gallery
Checkbook - Account Tracker Pros and Cons
- Simple interface makes recording income and expenses quick.
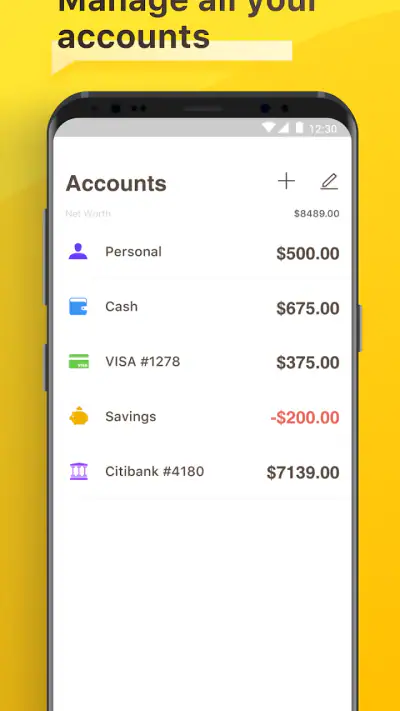
- Supports multiple accounts for tracking different balances.
- Recurring transactions reduce repetitive manual entries.
- Useful charts provide a clear view of spending habits.
- Budget tracking helps monitor limits and financial goals.
- Some advanced features may require an in-app purchase.
- No automatic bank synchronization for hands-free updates.
- Manual data entry can become time-consuming with frequent transactions.
- Limited sharing options may not suit families or joint finances.
- Users must maintain regular backups to avoid losing records.
Checkbook - Account Tracker Frequently Asked Questions
What is Checkbook - Account Tracker used for?
Checkbook - Account Tracker is designed to help you manage personal finances by recording income, expenses, deposits, withdrawals, and transfers in one place. After setting up an account, you can monitor your balance, review transaction history, and keep track of spending without connecting directly to a bank. It is useful for budgeting, checkbook balancing, and maintaining a simple offline-friendly financial record.
Does Checkbook - Account Tracker connect to my bank automatically?
The app is primarily intended for manual financial tracking, so users generally enter transactions themselves rather than allowing the application to access bank accounts automatically. This can be convenient if you prefer privacy or want to track cash, checks, and accounts that are not supported by bank synchronization. Before downloading, check the current store description for available synchronization or import features.
Can I manage multiple accounts and recurring transactions?
Checkbook - Account Tracker is suitable for users who need to organize more than one financial account, such as checking, savings, cash, or credit accounts, depending on the version and platform. You can typically record different transaction types and repeat common entries. However, the exact limits and recurring-transaction tools may vary between Android and iOS, so review the latest app listing.
Is my financial information safe when using the app?
Because this type of checkbook application may store sensitive information such as balances, transaction descriptions, and account details, you should use a strong device passcode and avoid entering unnecessary banking credentials. Manual tracking can reduce the need to share online banking access, but it does not automatically guarantee complete security. Check the app’s privacy policy, backup options, encryption claims, and permissions before use.
Is Checkbook - Account Tracker free to download, and are there additional costs?
The availability of free features, advertisements, premium upgrades, and subscription charges can differ according to the operating system and the current store version. Some users may be able to record basic transactions at no cost, while advanced tools such as unlimited accounts, reports, backups, or ad removal may require payment. Always inspect the Google Play or App Store pricing details before installing.














